6 Ways to Upgrade from HDB to Private Condo or EC
With cooling measures such as ABSD, MSR, TDSR, and tighter LTV, upgrading from HDB to private condo or executive condo is no longer a simple “what sticker price can I stretch to?” You also have to account for:
- ABSD on the next purchase (first vs second property treatment)
- How much mortgage the bank will allow while an HDB loan is still outstanding
- Cash vs CPF, temporary housing, and EC lock-in periods
You may also see ads that sound like this — “with income from S$7,000 you can upgrade without extra cash” — which is exactly why the numbers behind the structures matter:
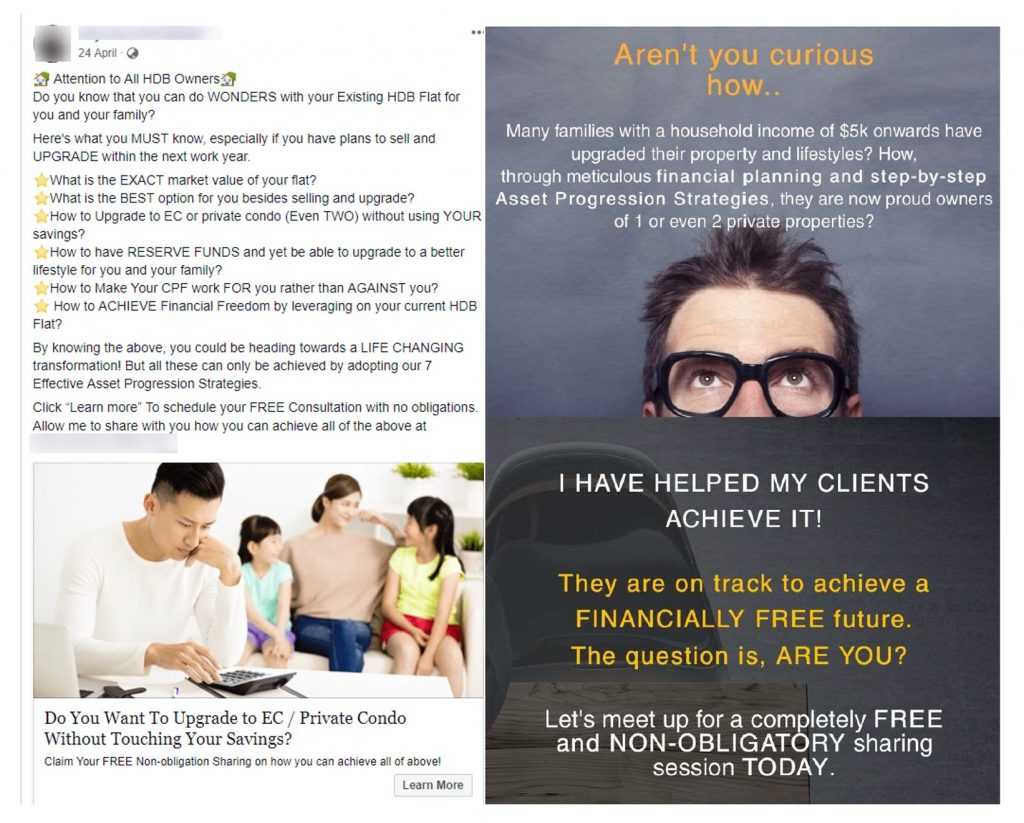
This article walks six upgrading options with a full worked example from Sep 2019:
- Keep HDB, buy private condo
- Sell HDB, buy private condo
- Sell HDB, keep cash-on-hand, buy private condo
- Upgrade to executive condo
- Upgrade to executive condo (keep cash-on-hand)
- Sell HDB, buy two private condos with cash buffer
Updated Sep 2026: The six structures still hold, but the dollar figures are from the original Sep 2019 worked example. See What has changed since 2019 (near the end) for the rule changes that move the numbers today. Re-run any plan with current IRAS / MAS / HDB rules and a bank’s indicative offer. This site does not calculate ABSD, LTV, TDSR, MSR, or affordability.
Profile of HDB owners (worked example)
A typical upgrader couple used in the original article:
| Kent | Jasmine | |
|---|---|---|
| Age | 35 | 32 |
| Monthly income | 7,500 | 6,000 |
| Monthly debt obligation | 1,100 | – |
| Current OA | 48,000 | 35,000 |
| Max home loan allowed (then) | Approx. S$855,000 | Approx. S$800,000 |
Assets in the example
| Amount | |
|---|---|
| Cash on hand | S$250,000 |
| OA from sales of HDB | S$302,000 |
| Cash proceed from sales of HDB | S$135,000 |
Option 1: Keep HDB, buy private
If they keep the HDB and buy a private condominium, the example max private value was only about S$460k — rarely useful in private stock.
| Amount | |
|---|---|
| Maximum property value buyable | S$463,714 |
| Loan required | S$208,671 |
| Total downpayment required (cash/CPF) | S$255,043 |
| Total fees and duties | S$67,157 |
Why so constrained? In the original framing: second-property LTV (then ~45% on the new loan while financing the HDB) and a higher ABSD tier as a second residential property (the article used 12% ABSD as then-applicable; for a Singapore Citizen’s second property it is 20% today). The lesson is structural: hold + buy is often loan- and ABSD-bound, not just “budget-bound.”
Option 2: Sell HDB, buy private condo
Selling first frees proceeds and typically restores first-property financing treatment (subject to timing and rules).
| Amount | |
|---|---|
| Maximum property value buyable | S$2,252,877 |
| Loan required | S$1,558,864 |
| Total downpayment required (cash/CPF) | S$694,013 |
| Total fees and duties | S$77,715 |
At ~S$2.25m theoretical max they would have many options — but maxing the sheet is unwise. Keep buffer for rates, job risk, and life plans.
Option 3: Sell HDB, keep cash-on-hand, buy private condo
Same as option 2, but do not spend the S$250k cash savings — only HDB sale proceeds + CPF/loan.
| Amount | |
|---|---|
| Maximum property value buyable | S$1,827,142 |
| Loan required | S$1,370,356 |
| Total downpayment required (cash/CPF) | S$456,786 |
| Total fees and duties | S$60,686 |
Without touching the S$250k buffer, the example still reaches ~S$1.83m private — often the healthier planning case.
Option 4: Upgrade to executive condo
With full cash + CPF deployment:
| Amount | |
|---|---|
| Maximum property value buyable | S$1,615,062 |
| Loan required | S$901,914 |
| Total downpayment required (cash/CPF) | S$713,148 |
| Total fees and duties | S$52,202 |
At ~S$1.6m, various EC sizes were in range at the time of writing (the original mentioned a 5-bedroom Premium example at a then-current launch).
Option 5: Upgrade to executive condo (keep cash-on-hand)
| Amount | |
|---|---|
| Maximum property value buyable | S$1,372,343 |
| Loan required | S$901,914 |
| Total downpayment required (cash/CPF) | S$470,429 |
| Total fees and duties | S$42,494 |
Conserving cash still left a workable EC ticket in the example (e.g. 4-bedroom Premium class product at then pricing).
Option 6: Sell one, buy two private condominiums
Can this be done? In the original sheet, yes in structure — with each spouse’s capacity modelled separately:
Kent’s affordability
| Amount | |
|---|---|
| Maximum property value buyable | S$1,009,549 |
| Loan required | S$757,162 |
| Total downpayment required (cash/CPF) | S$252,387 |
| Total fees and duties | S$27,982 |
Jasmine’s affordability
| Amount | |
|---|---|
| Maximum property value buyable | S$1,068,934 |
| Loan required | S$801,701 |
| Total downpayment required (cash/CPF) | S$267,233 |
| Total fees and duties | S$30,357 |
Individually, two mid-ticket privates plus residual cash (~S$190k in the original estimate) can appear. This is highly sensitive to ownership structure, ABSD, and TDSR under today’s rules — treat as a pattern, not a template.
What has changed since 2019
The structural lessons above still hold. The rules that change the numbers (as at Sep 2026):
| Rule | Sep 2019 example | Sep 2026 |
|---|---|---|
| ABSD, Singapore Citizen’s 2nd property | 12% | 20% (since Apr 2023) — Option 1 gets even tighter |
| Bank LTV (1st / 2nd / 3rd loan) | 75% / 45% / 35% | Unchanged |
| Interest rate used for the TDSR test | 3.5% | 4% (since Sep 2022) — lower maximum loans than the tables show |
| TDSR / MSR | 60% / 30% | 55% / 30% (MSR applies to ECs bought from developers) |
| BSD | 4% top tier | 5% and 6% bands above S$1.5m (since Feb 2023) |
| Seller’s Stamp Duty | 3-year holding period | 4 years, 16% down to 4% (for purchases from 4 Jul 2025) — matters for Option 6 exits |
| EC household income ceiling | S$14,000 (raised to S$16,000 later in Sep 2019) | S$16,000 for current ECs; S$18,000 for EC sites tendered from 24 Aug 2026 |
| EC MOP / deferred payment | 5 years / DPS available | 5 years and DPS on existing ECs; 10 years and no DPS for EC sites tendered from 8 May 2026 |
What you need to know (beyond the tables)
Family plan
Career breaks, schooling, and caregiving change safe leverage. A more conservative option is often wiser when income is about to step down.
Transition period
HDB → brand-new private
If you sell the HDB before private TOP and want first-property loan/ABSD treatment, you may need temporary accommodation for 2–3 years.
HDB → resale condo
Align HDB sale completion with private completion carefully to avoid double housing cost or forced temporary stays.
HDB → EC
Often the smoothest transition: collect EC keys, then sell HDB. IRAS has an ABSD remission for eligible HDB owners buying a new EC, and because you undertake to sell the flat within six months of taking possession of the EC, the bank can still lend up to the first-loan 75% — the key difference from buying private while keeping the HDB. On EC sites tendered from 8 May 2026, first-timers get 90% of units for the first two years, so upgraders (second-timers) have far less access to those launches.
Investment horizon / EC lock-in
EC can feel seamless on transition, but you may be locked in for years (build + MOP before free resale / next residential purchase in the usual way). For EC sites tendered from 8 May 2026 the MOP is 10 years, and full privatisation only comes after 15. Horizon must fit the family plan.
Wrapping up
| Option | Structural idea |
|---|---|
| 1 Keep HDB + buy private | Often ABSD + second-loan LTV crush max ticket |
| 2 Sell + buy private | Highest theoretical ticket; don’t max the sheet |
| 3 Sell + buy, keep cash | Often the balanced case |
| 4 EC full cash/CPF | Smooth transition; check eligibility & lock-in |
| 5 EC keep cash | Lower ticket, more buffer |
| 6 Dual private | Complex; ownership & ABSD must be re-checked live |
Before you upgrade: speak with a salesperson you trust, explore options and risks, and craft a plan for your constraints. Re-price everything with current IRAS/MAS/HDB numbers.
See also
- ABSD — second-property tax before you choose hold vs sell
- LTV & tenure — loan tiers while the HDB loan is still open
- 6 methods to analyze a property — once the path is clear, shortlist properly
Next step
HDB household weighing hold-and-buy vs sell-and-upgrade vs EC? Send the profile on WhatsApp. We map viable paths first — before showflats.